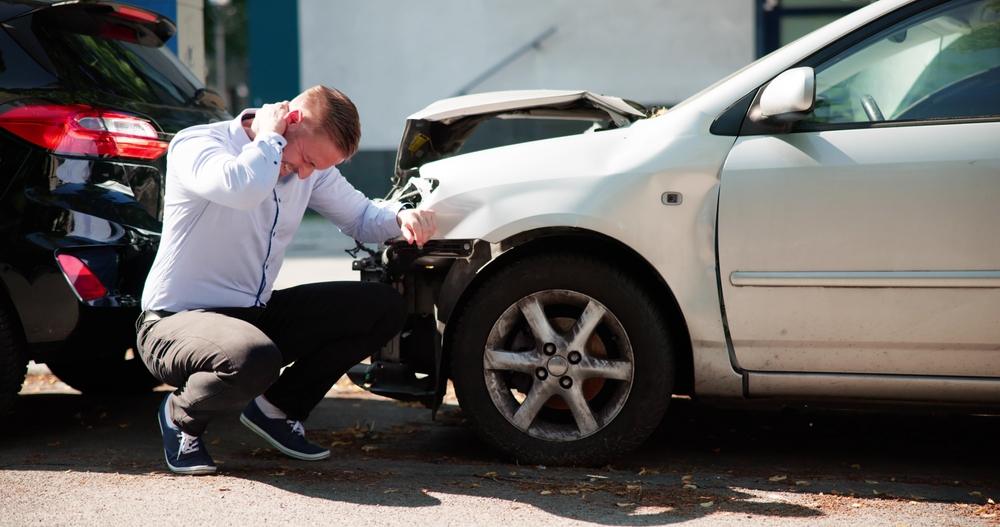
No-fault insurance changes who pays first after a serious car crash, but it does not eliminate every legal claim. Injured drivers usually seek medical and wage benefits through their own policies, regardless of who caused the collision. Severe injuries can still support a claim against the at-fault driver, subject to state-specific limits and evidence. Policy language, medical records, and crash evidence shape the outcome, so the initial decisions often affect the subsequent claim.
A person with serious injuries must determine whether no-fault benefits cover immediate losses and whether a separate liability claim remains available. A consultation with a Wesley Chapel car accident lawyer can clarify the injury threshold, review policy language, and preserve evidence before an insurer challenges causation, fault, or the extent of the harm. Early legal review also helps prevent missed filing deadlines.
No-Fault Coverage Pays First
No-fault insurance generally requires an injured person to seek initial benefits through personal injury protection coverage. Depending on the policy and state law, those benefits cover medical expenses, rehabilitation costs, and a portion of lost income. The payment does not depend on an immediate decision about which driver caused the collision. This structure helps address urgent bills, but coverage limits restrict the available amount. No-fault benefits also do not fully compensate for pain, permanent impairment, reduced earning capacity, or other long-term losses.
Medical payments coverage works differently. It pays certain medical bills for covered occupants, but it does not replace a broader injury claim. The policy language controls eligibility, limits, exclusions, and coordination with other insurance.
Serious Injuries Can Open a Liability Claim
No-fault states usually restrict lawsuits against an at-fault driver unless the injury meets a legal threshold. That threshold varies by state and policy. Common requirements include a permanent injury, significant disfigurement, substantial impairment, or a serious medical condition. The injury threshold determines whether an injured person can seek damages beyond no-fault benefits. A broken bone, spinal injury, traumatic brain injury, severe burn, or lasting nerve damage requires detailed medical proof. A diagnosis alone does not always establish that the injury meets the legal standard.
Fault Matters Even After a Threshold Is Met
Meeting an injury threshold does not remove the need to prove liability. A claimant still must connect the other driver’s conduct to the collision and resulting harm. Police reports, photographs, witness accounts, vehicle data, traffic-camera footage, and medical records can help establish that connection. The other driver’s insurer often examines speed, lane position, traffic signals, phone use, braking, and visibility. Small details can affect how the state’s negligence rules assign fault. Some states reduce compensation according to the injured person’s share of fault, while others restrict recovery when the claimant contributed to the crash. An injured driver should avoid guessing during an insurance interview. A recorded statement can create inconsistencies that later affect liability or injury arguments. Factual answers should remain accurate, brief, and limited to what the person knows.
Insurance Gaps Can Change the Recovery
An at-fault driver might carry liability coverage that does not pay the full value of a serious claim. Medical treatment, lost income, future care, and permanent limitations can quickly exceed policy limits. Uninsured and underinsured motorist coverage can provide another source of compensation when the responsible driver lacks sufficient insurance. The injured person’s policy may contain notice requirements, consent provisions, deadlines, and procedures for resolving disputes.
Evidence Protects the Claim
A serious injury claim becomes harder to prove as evidence disappears. Vehicle damage changes during repairs, surveillance footage gets deleted, and witnesses forget details. Photographs should show the vehicles, roadway, traffic controls, weather, lighting, visible injuries, and property damage. Medical care should continue according to the treating provider’s instructions. Records should describe symptoms, limitations, prescribed treatment, and missed work. A personal recovery journal can track pain, sleep problems, medication effects, household restrictions, and changes in daily activities.
Settlement discussions should wait until the medical outlook becomes clearer. An early payment can close the claim before doctors identify future treatment or permanent limitations. Legal review helps assess available coverage, damages, deadlines, and the injury threshold before a release is signed.
Conclusion
No-fault rules provide an initial route to medical and wage benefits, but serious injury claims often require a separate liability case. The deciding issues include the state’s injury threshold, proof of fault, insurance limits, medical documentation, and filing deadlines. After a major collision, injured drivers should report the loss, obtain consistent medical care, preserve crash evidence, and review every applicable policy before accepting payment. Those steps protect legal options while the injury’s full effects become clearer.