Winning an auto injury claim requires more than proving that a crash occurred. The injured person must connect the collision to a driver’s conduct, document medical harm, and show how the injury changed daily life. Insurers review gaps, inconsistent statements, treatment choices, and lost income records before valuing a demand. A sound case plan addresses these issues early, preserves useful evidence, and prepares for negotiation or court. The process begins with a disciplined review of the facts and responsibility in a case.
An effective review starts with the police report, photographs, witness accounts, and insurance information. Skilled lawyers who handle these matters, such as Aaron Sachs & Associates, can compare these records with medical notes and vehicle damage before discussing value. The review can highlight disputed facts and missing proof while giving the injured person a clear action plan on how to secure the compensation they deserve.
Establishing Responsibility
A claim must show why another driver caused the crash. Police reports often record traffic violations, statements, road conditions, and citations. These details provide an early account, but they do not replace independent proof.
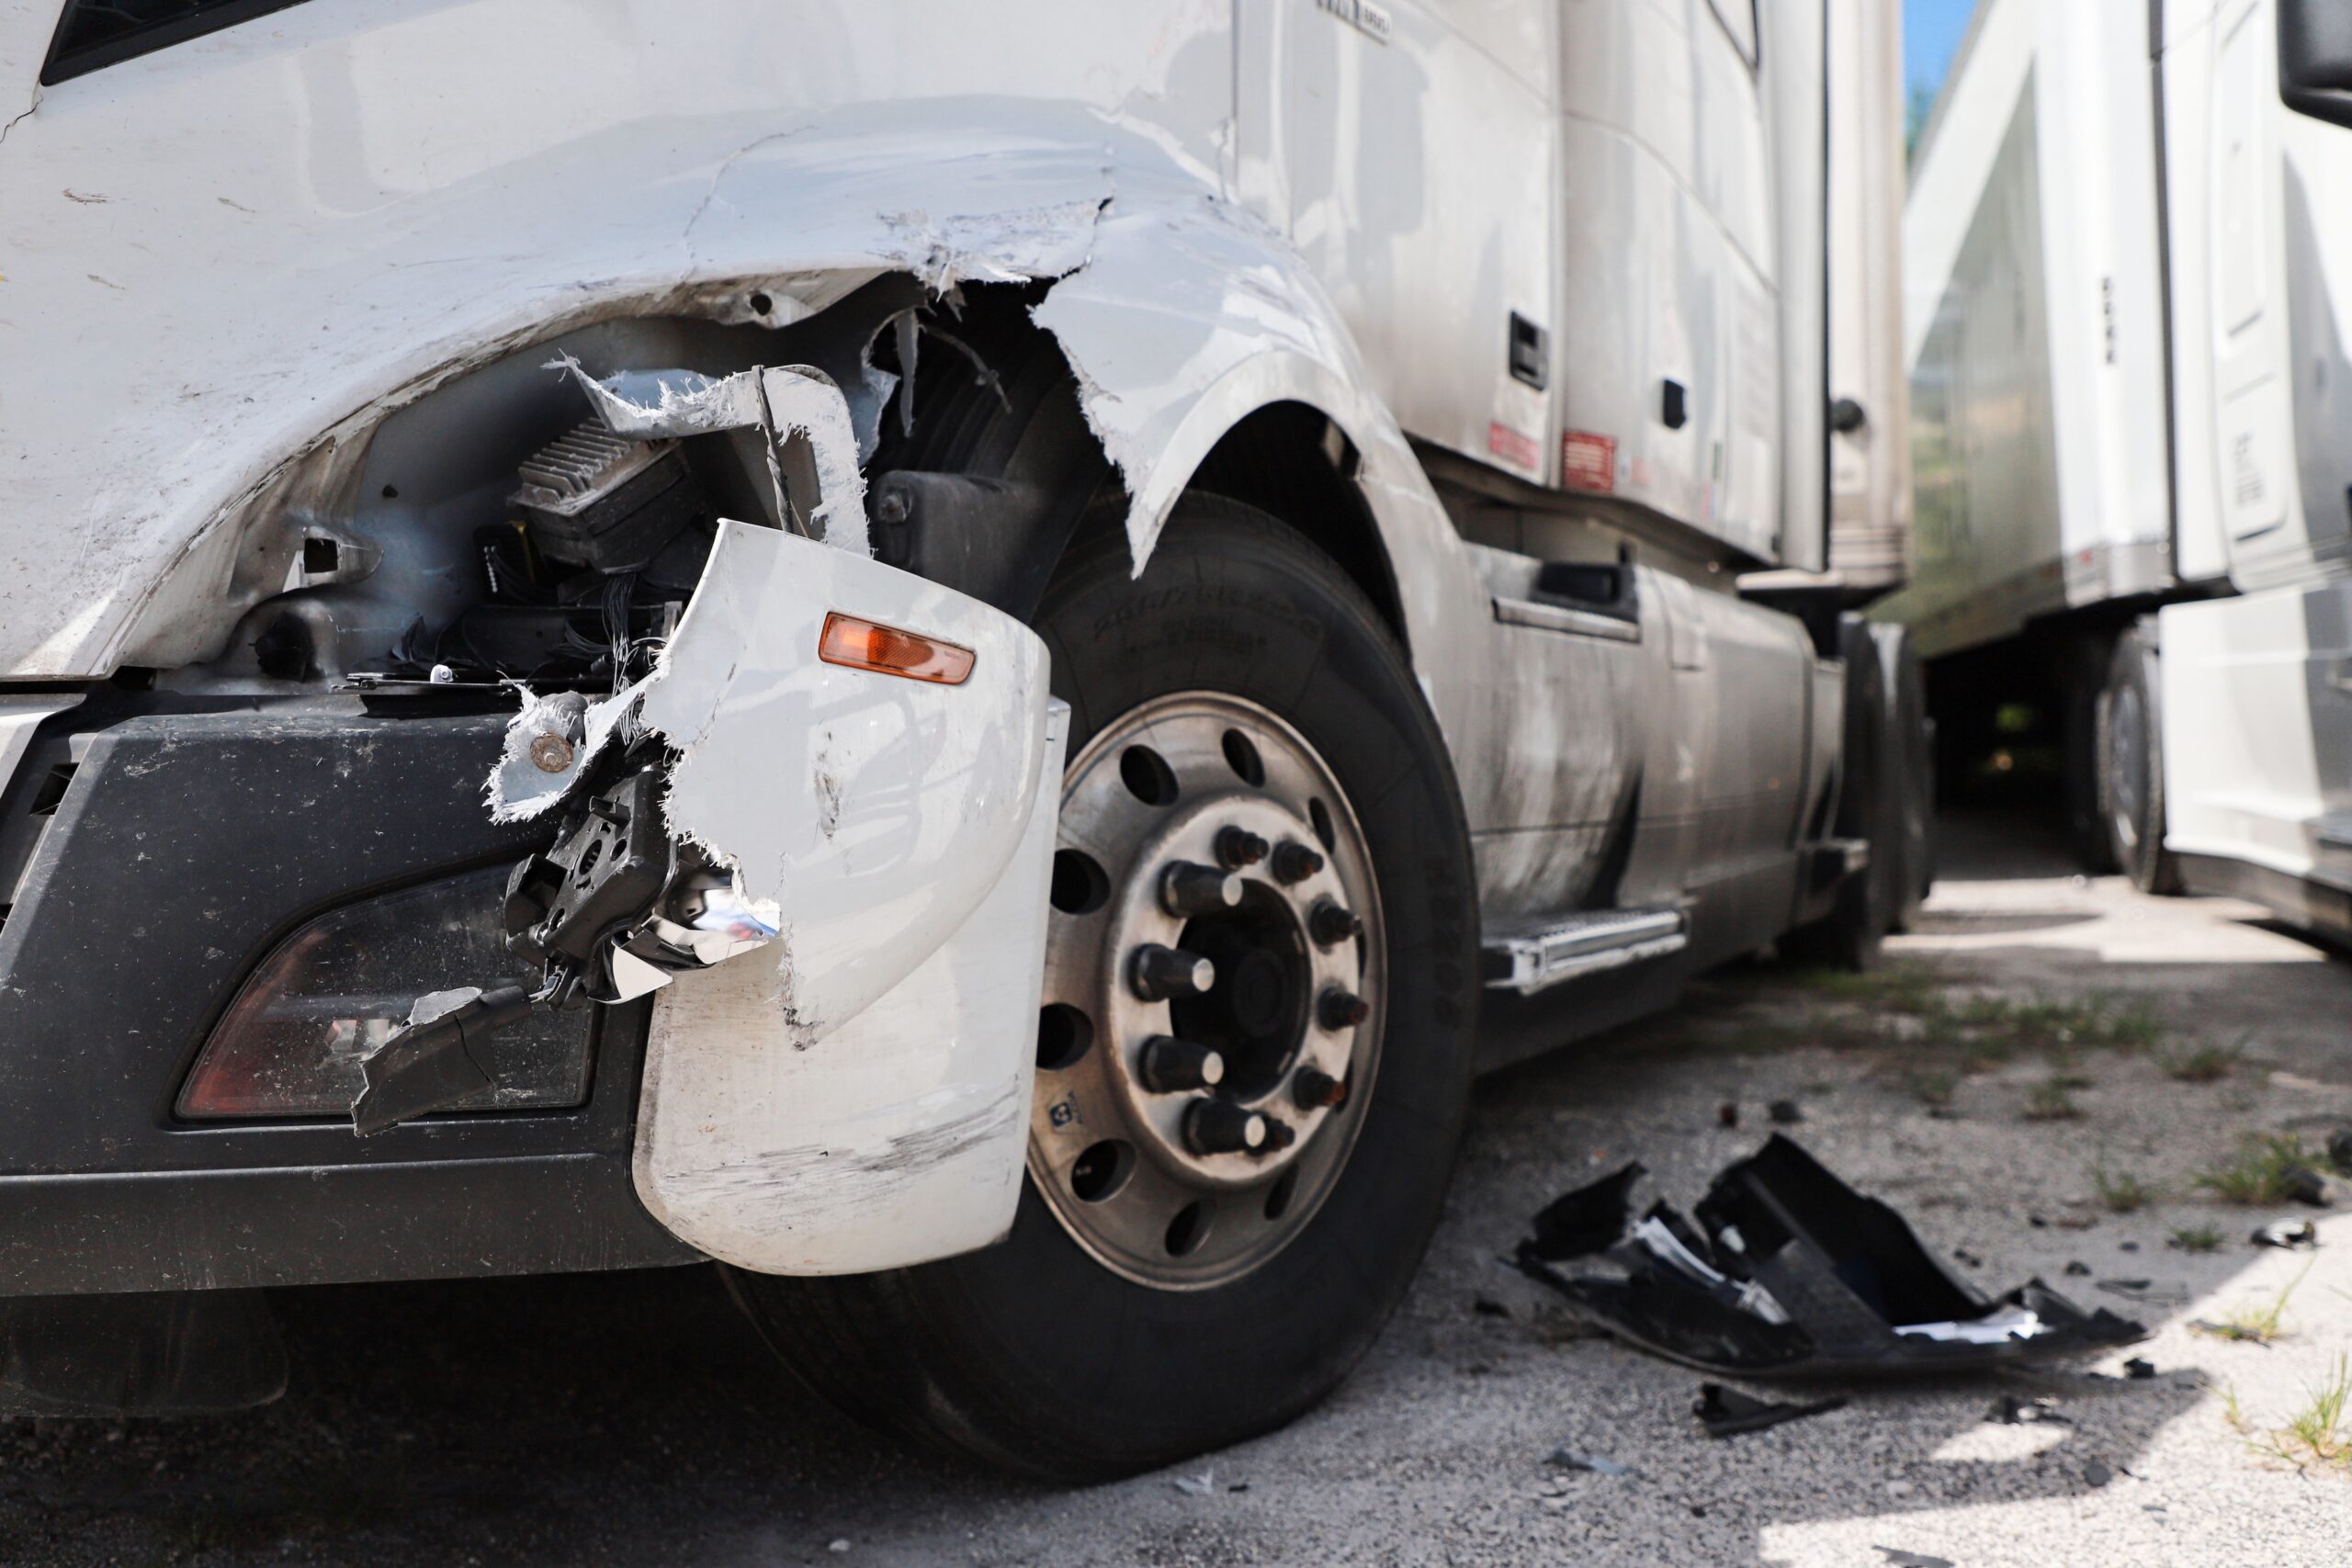
Photographs can show vehicle positions, impact points, skid marks, weather conditions, and roadway hazards. Witness accounts add context when drivers describe events differently. Traffic camera footage, phone records, and vehicle data can also clarify timing when these materials exist and lawfully become available.
The injured person should preserve every communication about the collision. Text messages, emails, repair estimates, and insurance statements can expose changes in the other driver’s account. Consistency matters because insurers compare each description against later records.
Documenting Medical Harm
Medical treatment creates the record that connects an injury to the crash. Prompt evaluation helps physicians identify symptoms, order appropriate tests, and establish a baseline after the collision. Delayed care gives an insurer an argument that another event caused the condition.
Each appointment should identify symptoms, limitations, diagnoses, treatment, and expected follow-up. The injured person should accurately describe work restrictions and daily difficulties. Providers need complete information to document the full effect of a person’s injury.
Financial records should support every claimed loss. Pay stubs, employer statements, tax documents, invoices, and receipts can show missed income and out-of-pocket expenses. Future losses require medical opinions or employment evidence explaining the various effects.
Calculating the Claim
A demand should separate economic losses from damages that lack a simple price tag. Economic losses include medical bills, rehabilitation costs, lost wages, property damage, and transportation expenses. Non-economic damages can address pain, reduced mobility, sleep disruption, and limits on ordinary activities.
The calculation should use actual records rather than rounded estimates. A medical billing summary can reveal charges, payments, health insurance adjustments, and balances. An employer statement can establish missed hours, wage rates, and available leave.
The injured person should avoid exaggeration. Unsupported claims give an insurer a reason to challenge the entire demand. A clear timeline, organized records, and consistent statements make the requested amount easier to assess.
Managing Insurance Negotiations
Insurance adjusters often request recorded statements, medical authorizations, and broad employment records. The injured person should review each request before providing information. A release that reaches unrelated medical history can expose private details and create confusion.
A written demand should explain liability, treatment, recovery, financial losses, and the requested payment. Supporting documents should appear in the same order as the argument. This organization lets the adjuster verify each major point without searching through unrelated material.
Negotiations should stay tied to evidence. An adjuster’s first proposal does not establish the claim’s value. The response should identify missing amounts, correct factual errors, and explain why the available records support a different figure.
Preparing for Court
A case may require litigation when the insurer denies responsibility or refuses fair compensation. Preparation begins before filing through witness interviews, record collection, expert review, and deadline tracking. State law controls filing periods, so the injured person should promptly confirm the applicable deadline.
Court preparation also affects settlement discussions. When the evidence is organized and witnesses understand the facts, each side can assess trial risks more accurately. The injured person should preserve social media posts and avoid public statements about the crash or recovery.
A lawsuit requires honest testimony and patience. Discovery can request medical records, employment information, photographs, and prior accident details. Accurate answers protect credibility and keep the case focused on the collision and its documented effects.
Conclusion
A winning auto injury claim follows a connected chain: responsibility, medical proof, financial records, and a supported demand. The injured person should preserve evidence, follow treatment instructions, record losses, and avoid casual statements to insurers.
Injured parties should create a dated crash file containing the report, photographs, bills, wage records, and correspondence. A qualified Missouri attorney can then review the file, identify gaps, and explain the available path before a filing deadline expires.